
Life insurance questions? Get clear answers before you choose.
Whether you're thinking about the people who depend on you, planning for final expenses, or reviewing a policy you already have, MedElevate Insurance can help you understand your options and what to consider before you decide.

We explain your options in plain language.
One-on-one conversations about your questions.
Serving Putnam County in person and all of Florida by phone or video.
Start where you are
What would you like life insurance to help with?
Learn how a death benefit could help the people who depend on you with bills, a mortgage, or everyday costs if you die.
Explore ways to prepare for funeral costs and reduce the money decisions your family may face.
Take a fresh look at a policy you already have, or help a parent or spouse understand their choices.
What we'll review
A conversation built around your needs, not a policy pitch.
Who or what would you want the money to help with?
Current policies, coverage through work, and possible gaps.
Premiums, how long coverage lasts, eligibility, exclusions, and limits.
Know your next steps. Applying is your choice.
Sometimes a helpful next step is keeping or updating the coverage you have, not buying something new. We'll help you ask the right questions.
Coverage types
Understand the differences before you compare.
- Coverage for a set number of years, such as 10, 20, or 30.
- It usually costs less at first than permanent coverage with the same death benefit.
- When the term ends, coverage stops unless the policy lets you renew or convert it, and renewal premiums are usually higher.
Good questions:
How long do I need coverage?
What happens when the term ends?
- Permanent coverage meant to last your whole life as long as you pay the required premiums.
- Premiums are usually higher than term for the same death benefit.
- Most whole life policies build cash value, which the policy describes.
- Borrowing against or withdrawing cash value lowers the death benefit, and ending the policy early can mean getting back less than you paid.
Good questions:
Which values are guaranteed?
What happens if I stop paying?
- Usually a smaller whole life policy meant to help your family pay for a funeral and other final costs.
- Your beneficiary decides how to use the money.
- Health questions, waiting periods, and age limits vary by policy.
Good questions:
How much coverage would help?
Is the full death benefit paid from day one?
- Detailed health questions
Some policies ask detailed health questions and may require a medical exam.
- Simplified issue
Simplified issue policies usually don't require a medical exam, but they do ask health questions, and your answers can affect whether you're approved and what you pay.
- Guaranteed issue
Guaranteed issue means the insurance company won't turn you down because of your health if you're within its age limits.
Final expense policies can use any of these approaches. Each policy explains its own rules.
How it works
How we help
Your family's needs, final expenses, coverage you have, and your budget.
We explain the types of coverage, the trade-offs, and what insurance companies may ask.
Understand coverage, premiums, policy conditions, and what happens next.
Apply only if you choose. Any application is subject to the insurance company's requirements and approval.
Before you apply
Questions worth answering before you apply
There's no single right amount. People often think about:
- debts such as a mortgage or loans
- how many years of income their family would need
- final expenses
- future costs like a child's education
- savings
- coverage they already have, including through work
Compare premiums and whether they stay level or can go up under the policy.
Compare short-term needs with lifelong ones.
We can explain general approaches insurance companies use. Please don't share health details on our web forms.
Compare benefits, limits, and costs before you surrender or replace anything.
Ask a question
Tell us what you'd like to talk about, and we'll get back to you by phone or email.
Common questions
Does Medicare include life insurance?
No. Medicare helps pay for health care. Life insurance is a separate policy that pays a death benefit to the people you name, under the policy's terms. Whether you want it depends on who and what you'd want the money to help with.
What's the difference between term and whole life insurance?
Term life covers a set number of years. Whole life is designed to last your whole life as long as you pay the required premiums, and most policies build cash value. Premiums, features, and limits vary by policy.
Can I get coverage if I have a health condition?
Possibly. Some policies use full medical underwriting, some ask a shorter set of health questions, and some are guaranteed issue within age limits. Guaranteed issue policies usually cost more and often pay a limited benefit if death from illness happens during the first few years. We can talk about which kinds of policies may be worth looking at.
What is final expense insurance?
It's usually a smaller whole life policy meant to help pay for a funeral and other final costs. It isn't a separate kind of insurance. Your beneficiary receives the money and decides how to use it.
What if I already have a policy?
We can go over its death benefit, cost, beneficiaries, how long it lasts, and its limits. Don't cancel or stop paying an existing policy until a new one has been approved and issued and you've reviewed it. A new policy may cost more, restart the 2-year contestability period, and have new waiting periods. If a new policy would replace or reduce one you have, Florida requires a replacement notice with the application.
Can I change my mind after I buy a policy?
In Florida, after a life insurance policy is delivered, you generally have at least 14 days to review it. If you're not satisfied, you can return it for a full refund of the premium you paid. Check your policy for the exact period and how to return it.
What is the contestability period?
During the first 2 years a policy is in force, the insurance company can generally review and challenge the policy if the application left out or misstated important information. After that, Florida law generally doesn't allow it, with some exceptions. That's why it matters to answer every application question completely and accurately.
Who should I name as my beneficiary?
That's your decision. You can usually name a main beneficiary and backups. Review your choices after big life changes, like marriage, divorce, a birth, or a death in the family, and let your beneficiaries know the policy exists and which company issued it.
What should I have ready for a call?
Any life insurance you already have (including coverage through work), a rough monthly budget, who you'd want to receive the money, and your questions. Please don't send medical records or Social Security numbers by email or web form.
- Florida Department of Financial Services Insurance Consumer Helpline: 1-877-693-5236 (1-877-MY-FL-CFO).
- Read the Department's Life Insurance Overview (opens in a new tab) Opens in a new tab..
- Check any agent's license with the licensee search (opens in a new tab).
Talk through your goals and questions with a licensed Florida insurance agent and learn what your next steps could be.
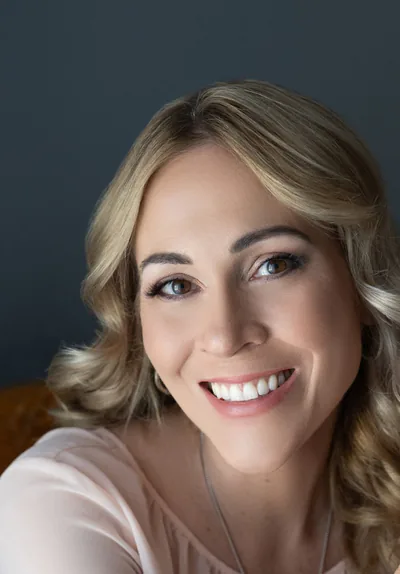 Molly Stanton | Licensed Florida Insurance Agent
About this page
This page gives general information about life insurance. It isn't an offer of any specific policy. Policies are issued by insurance companies, not by MedElevate Insurance.
Coverage, premiums, benefits, limitations, and underwriting vary by insurance company, policy, and applicant. Not every policy is available to every applicant, and applying doesn't guarantee approval. Your policy sets the actual terms.
We help Florida residents only. We don't give tax, legal, investment, or financial planning advice. Life insurance is not a Medicare plan; the Medicare information in our footer applies only to Medicare plans.
MedElevate Insurance is a licensed Florida insurance agency (Florida agency license #L138486). Molly Stanton | Licensed Florida Insurance Agent.
Last reviewed: October 11, 2026