
- Original Medicare includes Part A (hospital insurance) and Part B (medical insurance).
- You can generally see any doctor or hospital in the U.S. that accepts Medicare.
- You can add a separate Part D drug plan.
- A Medicare Supplement Insurance (Medigap) policy from a private company may help pay some of your out-of-pocket costs, depending on when you apply and your rights to buy one.
LOCAL MEDICARE GUIDANCE IN PUTNAM COUNTY · STATEWIDE BY PHONE OR VIDEO
Medicare help, made easier to understand.
Have questions about doctors, prescriptions, coverage, or costs? Start with clear answers.
Whether you're new to Medicare or reviewing coverage you already have, we can talk through your options and what matters most to you. A conversation can help even if you keep your current coverage. I'm Molly Stanton, a licensed Florida insurance agent serving Putnam County in person and people anywhere in Florida by phone or video.

What brings you here today?
Getting ready for Medicare? Learn about enrollment timing and what to consider before you choose coverage.
Already have Medicare? Review your doctors, prescriptions, costs, and coverage needs before deciding whether to make a change.
Learn how drug lists, pharmacies, and plan rules can affect what you pay for medicines.
Received a notice that your Medicare plan is ending or changing? Find out what to review and which deadlines may apply.
If you have certain serious chronic conditions, a Chronic Condition Special Needs Plan (C-SNP) may be an option where one is available. Eligibility rules apply, and the plan must confirm your condition.
Understanding Your Medicare Coverage Choices
There are two main ways to get your Medicare coverage. The differences can affect which doctors you can see, how you get prescriptions covered, and how you pay for care.
- Medicare Advantage is another way to get your Part A and Part B coverage, through a Medicare-approved plan from a private company.
- You need Part A and Part B and must live in the plan's service area.
- Most plans include Part D drug coverage.
- Provider networks, referrals, prior authorization, out-of-pocket costs, and benefits vary by plan.
Medigap works with Original Medicare, not Medicare Advantage. Neither choice is better for everyone. What fits depends on your doctors, prescriptions, costs, and how you like to get care.
- Part A (hospital insurance) helps cover inpatient hospital stays, skilled nursing facility care, hospice, and some home health care.
- Part B (medical insurance) helps cover doctor visits, outpatient care, many preventive services, and medical equipment.
- Part C (Medicare Advantage) is a Medicare-approved plan from a private company that provides your Part A and Part B coverage, and usually Part D.
- Part D (drug coverage) helps cover prescription drugs. You can get it through a separate drug plan or through most Medicare Advantage plans.
Source: Medicare.gov, Parts of Medicare (opens in a new tab).
- Initial Enrollment Period: 7 months around your 65th birthday: the 3 months before your birthday month, your birthday month, and the 3 months after.
- General Enrollment Period: January 1 to March 31 each year, if you missed signing up for Part A or Part B when you were first eligible. Coverage starts the month after you sign up.
- Open Enrollment Period: October 15 to December 7 each year. You can join, switch, or drop a Medicare Advantage or Part D plan. Coverage starts January 1.
- Medicare Advantage Open Enrollment Period: January 1 to March 31 each year, only if you're already in a Medicare Advantage plan. You can switch to another Medicare Advantage plan, or go back to Original Medicare and join a drug plan.
- Special Enrollment Periods: certain life events, like moving or losing other coverage, may let you make changes at other times.
If you're still working and have coverage through a job, different timing may apply. Signing up late for Part B or Part D can mean a late enrollment penalty, so check your dates.
Your Medigap Open Enrollment Period lasts 6 months and starts the first month you have Part B and are 65 or older. During that time, an insurance company can't turn you down or charge you more because of your health. It happens only once. After it ends, you may be turned down or charged more unless you have a special right to buy a policy.
- In Florida, people under 65 who have Part B because of a disability or End-Stage Renal Disease (ESRD) also have a 6-month Medigap open enrollment period starting when their Part B starts, and another when they turn 65.
- Florida also gives people 65 and older a 2-month window after group health coverage ends.
- Prices for people under 65 are often higher.
- A waiting period for pre-existing conditions may apply in some cases.
- Ask the insurance company.
Sources: Medicare.gov, Medigap basics (opens in a new tab); Florida Office of Insurance Regulation, 2026 Medigap FAQ (opens in a new tab); Section 627.6741, Florida Statutes (opens in a new tab).
If you have limited income and resources, you may qualify for help:
Extra Help helps pay for Medicare drug coverage. Some people qualify automatically. Others can apply through Social Security.
Apply for Extra Help at Social Security (opens in a new tab)Learn about help with drug costs on Medicare.gov (opens in a new tab)
Medicare Savings Programs may help pay Part A and Part B premiums and some other costs. You apply through your state Medicaid office.
Learn about Medicare Savings Programs on Medicare.gov (opens in a new tab)
When you apply for Extra Help, Social Security can also send your information to your state to start a Medicare Savings Program application. Questions? Call Medicare at 1-800-MEDICARE (1-800-633-4227, TTY 1-877-486-2048) or Social Security at 1-800-772-1213 (TTY 1-800-325-0778).
A plan's monthly premium is only one piece of the picture. We can look at the details that could make a difference in your everyday care.
- Your doctors, specialists, and hospitals
- Your prescriptions and preferred pharmacies
- Premiums, deductibles, copays, and potential out-of-pocket costs
- Provider networks, referrals, and prior authorization requirements
- How your coverage works if you spend time away from home
- Changes to your coverage and questions about enrollment timing
Available plans and benefits depend on your location and eligibility. Coverage and costs should be confirmed using current plan documents.
Turning 65 or becoming eligible earlier? We can help you understand the basic choices and enrollment steps.
Wondering whether your coverage still fits? We can review changes and what matters before you decide.
Supporting a parent, spouse, or family member? We can help you understand the questions to ask and the next steps. Any plan discussion or enrollment decisions need the person with Medicare or their authorized representative.
Have your care needs changed? We can look at how your current coverage works for your care and explain which enrollment rules may apply.
Medicare's Plan Finder at Medicare.gov/plan-compare (opens in a new tab) lets you look up plans in your area, enter your prescriptions, and compare costs and coverage. You can also call 1-800-MEDICARE (1-800-633-4227), TTY 1-877-486-2048, 24 hours a day, 7 days a week. We're happy to go through it with you if you'd like help.
When should I enroll in Medicare?
Most people first sign up during their Initial Enrollment Period, a 7-month window that includes the 3 months before the month you turn 65, your birthday month, and the 3 months after. If you or your spouse are still working and have job-based coverage, your timing may be different. Once you have Medicare, you can join or change health and drug plans each year from October 15 through December 7. Other enrollment periods may apply in certain situations. We can help you figure out which dates apply to you.
What's the difference between Original Medicare and Medicare Advantage?
Original Medicare includes Part A and Part B, with optional separate drug coverage and possible Medigap coverage. Medicare Advantage is a Medicare-approved private-plan alternative for getting your Part A and Part B coverage, and most plans also include drug coverage. Costs, provider rules, and coverage details differ.
Can I keep my doctors and prescriptions?
That depends on the coverage you choose. With Original Medicare, you can generally see providers that accept Medicare. Medicare Advantage plans may have provider networks. Drug coverage depends on the plan's covered drug list and pharmacy rules. We can help you check those details.
Do I need Medicare Supplement Insurance (Medigap)?
Medigap is optional coverage, sold by private insurance companies, that may help pay some costs in Original Medicare. It doesn't work with Medicare Advantage. The usual time to buy is your 6-month Medigap Open Enrollment Period, which starts the first month you have Part B and are 65 or older. During that time, a company can't turn you down or charge you more because of your health. Outside that window, you may be turned down or charged more unless you have a special right to buy a policy.
What if my plan is ending or I have a chronic condition?
If your plan is leaving Medicare or your area, you may have a Special Enrollment Period and certain Medigap rights. The notice from your plan explains the dates. If you have certain serious chronic conditions, a Chronic Condition Special Needs Plan (C-SNP) may be an option where one is available. Each situation has its own rules. See our pages on plans that are ending and on chronic conditions and Medicare.
How does MedElevate Insurance get paid?
We're paid by the insurance companies whose plans we offer, not by you. Scheduling an appointment doesn't obligate you to enroll in anything. If you'd like, we can use a first 15-minute call to talk through your questions and decide on next steps together.
Sources: Medicare.gov, Your coverage options (opens in a new tab) and Joining a plan (opens in a new tab).
- 1
Start with your questions.
Tell us what you're trying to understand and what matters most.
- 2
Confirm what you'd like to discuss.
Before we talk about specific plans, Medicare rules ask us to confirm with you which types of plans you'd like to discuss. This is called a Scope of Appointment. It doesn't sign you up for anything.
- 3
Review the available options.
We can explain relevant coverage choices and what to check before deciding.
- 4
Choose your next step.
Keep your coverage, look at another option, or come back with more questions. The decision is yours.
Anywhere in Florida? We can meet by phone or video.Schedule a call (opens in a new tab)
- Your Medicare card and any other insurance cards
- A list of your prescriptions, with doses and how often you take them
- Your doctors, specialists, and preferred pharmacies
- Any letters or notices from your current plan, such as an Annual Notice of Change
Please don't send your Medicare number or health details through our website. We'll go over what's needed when we talk.
Start with a 15-minute introductory call.
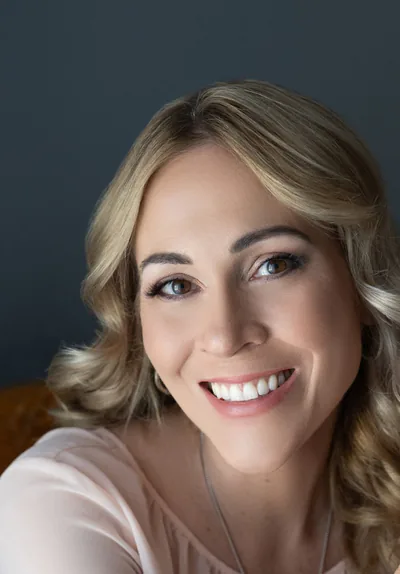 Molly Stanton | Licensed Florida Insurance Agent
Last reviewed: October 2026